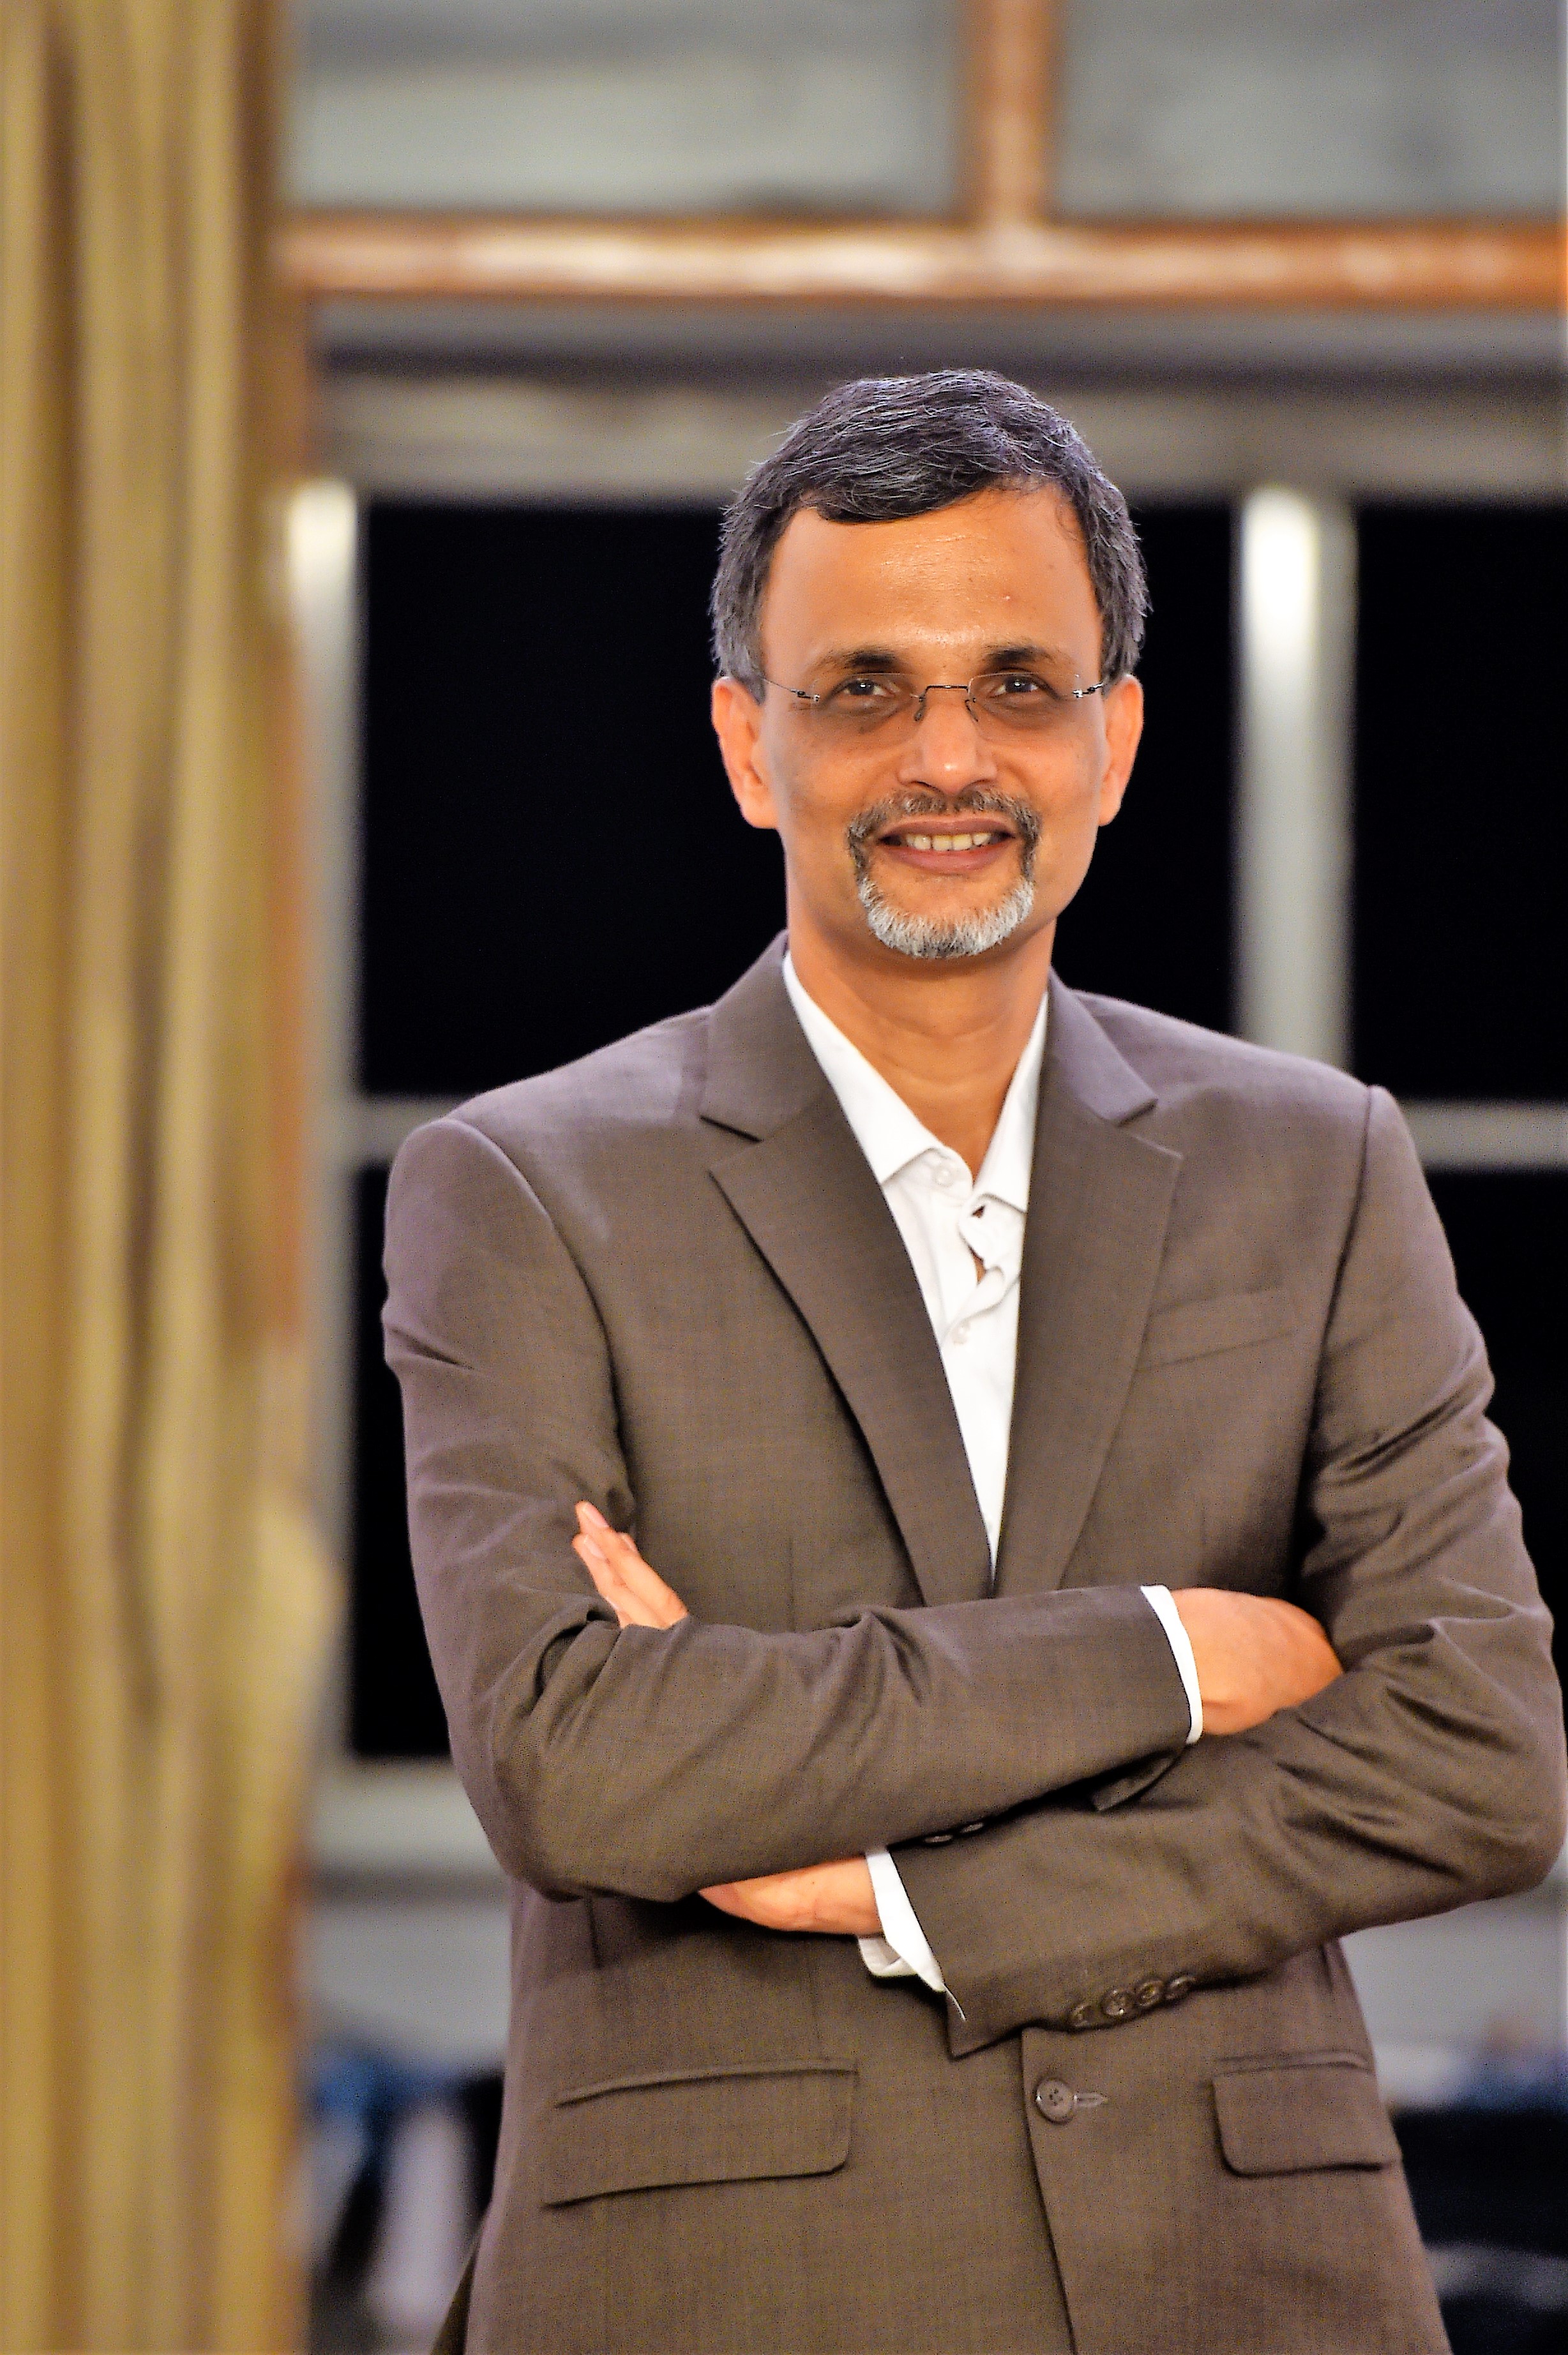
V. Anantha Nageswaran
Chief Economic Advisor, Government of India
“You cannot just buy the fab. You have to build the entire nervous system around it.”
— V. Anantha Nageswaran
Medium and high-tech manufacturing: 46%+ of India’s manufacturing value added.
RDI Fund: ₹1 lakh crore to drive private deep-tech R&D and process innovation.
India’s GDP target: $10 trillion by 2047 — requiring capability ownership, not just assembly.
What replaced it is a system where manufacturing underwrites state survival. Competitiveness is now defined by technological sovereignty, supply chain security, and geopolitical leverage. India is rebuilding its macroeconomic architecture around this reality.
At the centre of that transition sits V. Anantha Nageswaran, the Chief Economic Advisor to the Government of India. The mandate is insulation at scale. The cost of failure is no longer cyclical. It is structural dependence.
India is already moving. Medium and high-technology manufacturing now accounts for over 46% of total manufacturing value added. The focus has shifted from output to capability.
Industrial Apprenticeship
Entering a global value chain generates scale. Moving up inside it generates power.
India’s expanding footprint in electronics, pharmaceuticals, and engineering goods shows that integration is working. But integration is not the destination. Ownership is.
China’s ascent followed a clear sequence—assembly, then engineering, then control. OEM to ODM to OBM. An industrial apprenticeship executed at scale.
India’s model will differ in structure, but not in physics. Participation must translate into capability. Assembly must lead to design. Design must lead to ownership.
You don’t remain at the bottom of a value chain. You either climb—or you get locked in.
Architecture of Clusters
Industrial dominance is built on density.
Factories compete as part of a grid—suppliers, logistics, working capital, labour, governance. If that grid slows down, the factory is already losing.
A shipment delayed at a state border is not a logistics issue. It is a margin loss. Supplier lag doesn’t inconvenience operations. It destabilises production.
This is where policy is being forced to move beyond incentives. The ₹1 lakh crore Research, Development & Innovation Fund is about pushing private capital into real friction—process engineering, embedded systems, shop-floor innovation.
At this level, innovation is operational survival.
Silicon Battleground
Semiconductors sit underneath everything—consumer electronics, industrial systems, defence infrastructure. If you don’t control the chips, you don’t control the system.
The India Semiconductor Mission (ISM 2.0) is a capability build-out. Fabrication plants are necessary. They are not sufficient.
“You cannot just buy the fab,” Nageswaran says. “You have to build the entire nervous system around it.”
Design. Materials. Packaging. Workforce. Without that stack, a fab is an asset. With it, it becomes leverage.
Capital With A Clock
The shift reaches the workforce.
Advanced manufacturing breaks the traditional definition of labour. It demands hybrid capability—technical skill layered with adaptability. India’s demographic advantage only converts if it aligns with mechatronics, automation, and real industrial workflows.
The state will intervene. It has to. Entry barriers are too high and uncertainty too deep. But that intervention is conditional.
“Capital comes with a clock.”
Support will be time-bound. Performance-linked. Export-driven. The tension is structural—industry seeks protection, but the state cannot afford permanence.
The crutch will be removed. What remains will determine competitiveness.
What All This is For
Manufacturing absorbs labour and lifts productivity, but those are secondary effects. The primary function is removing dependence.
The transition underway—from assembly to capability, from participation to control—is the mechanism through which India secures economic sovereignty.
A $10 trillion economy cannot be assembled. It has to be engineered—end to end.
Key Takeaways
46%
The Pivot Metric: current share of medium- and high-technology manufacturing in India’s total manufacturing value added.
₹1L Cr
The Capital Injection: scale of the RDI Fund designed to force private capital into deep-tech innovation.
The Ascent Physics: India is replicating the strict physics of industrial mastery:
Assemble: Learn the process.
Engineer: Acquire the capability.
Own: Secure global leadership.
Solutions Spotlight
Field Mechanics: Engineering the Grid
The Silicon Nervous System
ISM 2.0 moves beyond just subsidising fabrication plants. It is building the requisite capability matrix—chip design, specialised materials, and packaging—to ensure actual technological resilience rather than just physical manufacturing capacity.
Cluster Density
The state is shifting focus from cheap land to supplier density. The effectiveness of industrial hubs will now be dictated by working capital velocity, truck movement, and supplier lag, not just tax holidays.
Capitalising the Workforce
Demographic advantage is being converted into mechatronic leverage through modular skilling, industry-linked vocational training, and the aggressive integration of female labour force participation in advanced manufacturing setups.
The Capability Doctrine
Ownership Over Scale
Entering a global supply chain generates employment. Upgrading inside it generates power.
Density Dictates Speed
Factories operate inside grids. If the grid is slow, the factory bleeds.
Capital Comes With a Clock
The tension is permanent. Industry wants protection; the state demands exports. Competitiveness relies on ruthless firm-level efficiency, because the subsidy crutch will be removed.
Manufacturing is Sovereignty
The transition from assembly to capability is the physical mechanism of Viksit Bharat.
Excerpts from the Interview with V. Anantha Nageswaran
Medium and high-tech manufacturing now accounts for over 46% of the sector’s value added. Why is this transition critical right now?
Because the global manufacturing landscape has undergone a structural reset. Competitiveness is no longer defined just by efficiency and cost arbitrage. It is increasingly shaped by geopolitics, supply chain security, and technological sovereignty. In this environment, manufacturing is not just a growth engine—it is the core lever of a nation’s strategic resilience.
You’ve pointed to China’s industrial transformation as a useful analytical lens. What is the specific lesson India needs to extract?
It is the concept of the industrial apprenticeship. China followed a staged progression—from assembly to acquiring design capabilities and eventually building indigenous brands. While India’s institutional context is different, the physics are the same: global integration must translate into capability accumulation. You must secure upward mobility within the value chain.
Let’s talk about semiconductors and ISM 2.0. Is the fabrication plant the endgame?
Fabrication capacity is strategically valuable, but it is not the entire equation. Long-term competitiveness depends equally on strengths in chip design, specialised materials, manufacturing services, and a highly skilled technical workforce. You cannot just buy the fab. You have to build the entire nervous system around it.
The state is intervening heavily with capital and incentives. How do we prevent permanent dependence on subsidies?
By ensuring that capital comes with a clock. Strategic support must remain time-bound, performance-linked, and aggressively export-orientated. Over the longer term, competitiveness will not depend on subsidies. It will depend on improvements in regulatory predictability, logistics efficiency, and firm-level technological upgrading.