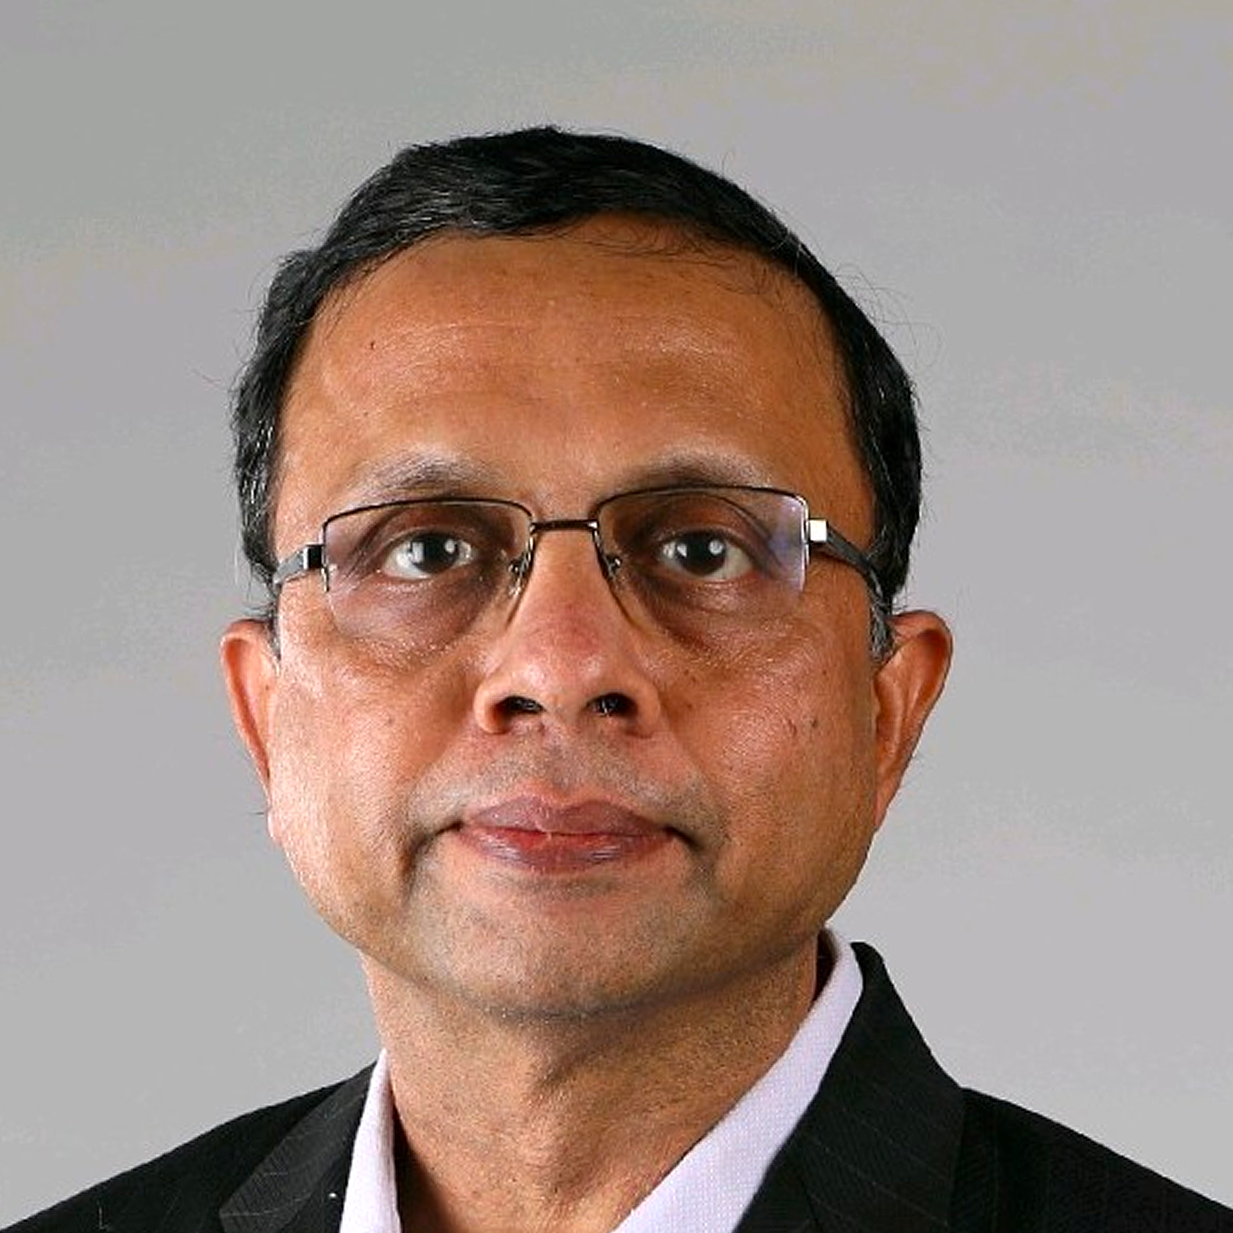
Sanjeev Agarwal
Executive Director & Chief of Manufacturing, Lava International
“When you use a reference design, you are assembling someone else’s vision.”
— Sanjeev Agarwal
India’s current BoM localisation: 20–25%. Strategic threshold: 50–60%.
Lava has built full-cycle product architecture capabilities in India since 2018.
Target: $500 billion electronics output vision requiring vertical depth.
India built manufacturing scale. It did not build control. For over a decade, the domestic electronics sector operated on an assembly-led model—integrating foreign logic through Indian labour at scale. That phase delivered volume. It did not deliver ownership.
As output advances toward a $500 billion vision, the mandate has shifted. At the centre of this transition is Sanjeev Agarwal, Executive Director and Chief of Manufacturing at Lava International. While global incumbents continue to treat India primarily as a consumption market, the objective has moved beyond mere production toward systemic authorship.
White-label Trap
The structural weakness of Indian hardware has been the “white-label” model. Domestic brands operated through foreign Independent Design Houses (IDHs), adopting reference designs with zero room for differentiation. Innovation was capped. Control stayed external.
“When you use a reference design, you are assembling someone else’s vision,” Agarwal notes.
Lava’s response was to pull design in-house. Since 2018, it has built full-cycle product architecture capabilities within India. Product definition, hardware engineering, and software integration now sit inside the same loop. If you don’t design the system, you don’t control the outcome.
Design Shift
Design initiates control, but the supply chain determines whether it holds. India has localised assembly, but it has not yet localised value. Currently, India localises roughly 20–25% of its bill of materials (BoM); the strategic threshold required for independence is 50–60%.
The constraint is not assembly capacity—it is how much of the system is actually owned.
60 Per Cent Threshold
Silicon, sensors, and display modules remain the primary dependency layers. Lava’s approach is to aggregate demand across sectors—mobile, automotive, and TVs—to make component manufacturing viable at home.
Displays, camera modules, and PCBs are the layers where value concentrates. When demand converges across industries, scale becomes a lever for domestic depth.
“Our trajectory requires vertical depth. We must descend into the core layers to engineer differentiated assets and outpace global incumbents.”
Manufacturing Discipline
Cost defined the first phase of India’s story. Discipline will define the next. In high-precision electronics, quality is binary.
“Manufacturing operates as an army,” says Agarwal. “It demands a culture of absolute discipline—because quality is no longer a spectrum. It is either a complete success or a complete failure.”
To meet this standard, the factory floor is moving from a labour pool to a managed system. Skilling has been pulled inside—training operators to become technical supervisors who can deliver consistent global-quality output. Performance expectations are rising; tolerance for failure is falling. Labour executes. Systems decide.
Silicon Inevitability
At the system level, control converges on two points: the processor and the operating system. Globally, only two to three companies control mobile processors. That is where real control sits. The processor decides the system; everything else is selectable.
“It is not easy—and it will not be immediate,” Agarwal says. “But the path is defined.”
India’s semiconductor journey has begun with packaging and design partnerships, but real independence requires moving into the processor layer. Without the processor, there is no control. With it, the system is no longer dependent.
Global competitiveness in electronics will not be determined by how much India assembles—but by how much of the system it owns.
Solutions Spotlight
In-House IDH
Building internal independent design house capabilities to break the “white-label” dependency on foreign blueprints.
Cross-Sector Sourcing
Aggregating demand for displays and camera modules across industries to make local high-value component manufacturing viable.
Vertical Integration
Moving from assembly to 60% localisation to secure the supply chain against global shocks.
System Realities
Localisation Metrics
20–25% localisation is assembly. Competitive advantage begins beyond 50%.
The Silicon Rule
Processors define the system. Everything else is integrated around them.
Platform Logic
Component scale is cross-sector. Displays, sensors, and PCBs become viable only when demand aggregates across mobile and automotive.
The Architecture Gap
Design capability is the constraint. Manufacturing scale already exists; architecture does not.
The Binary Standard
Quality is binary. There is no tolerance band in high-precision electronics.